France’s Robotics Map: 16 Companies Beyond the Humanoid
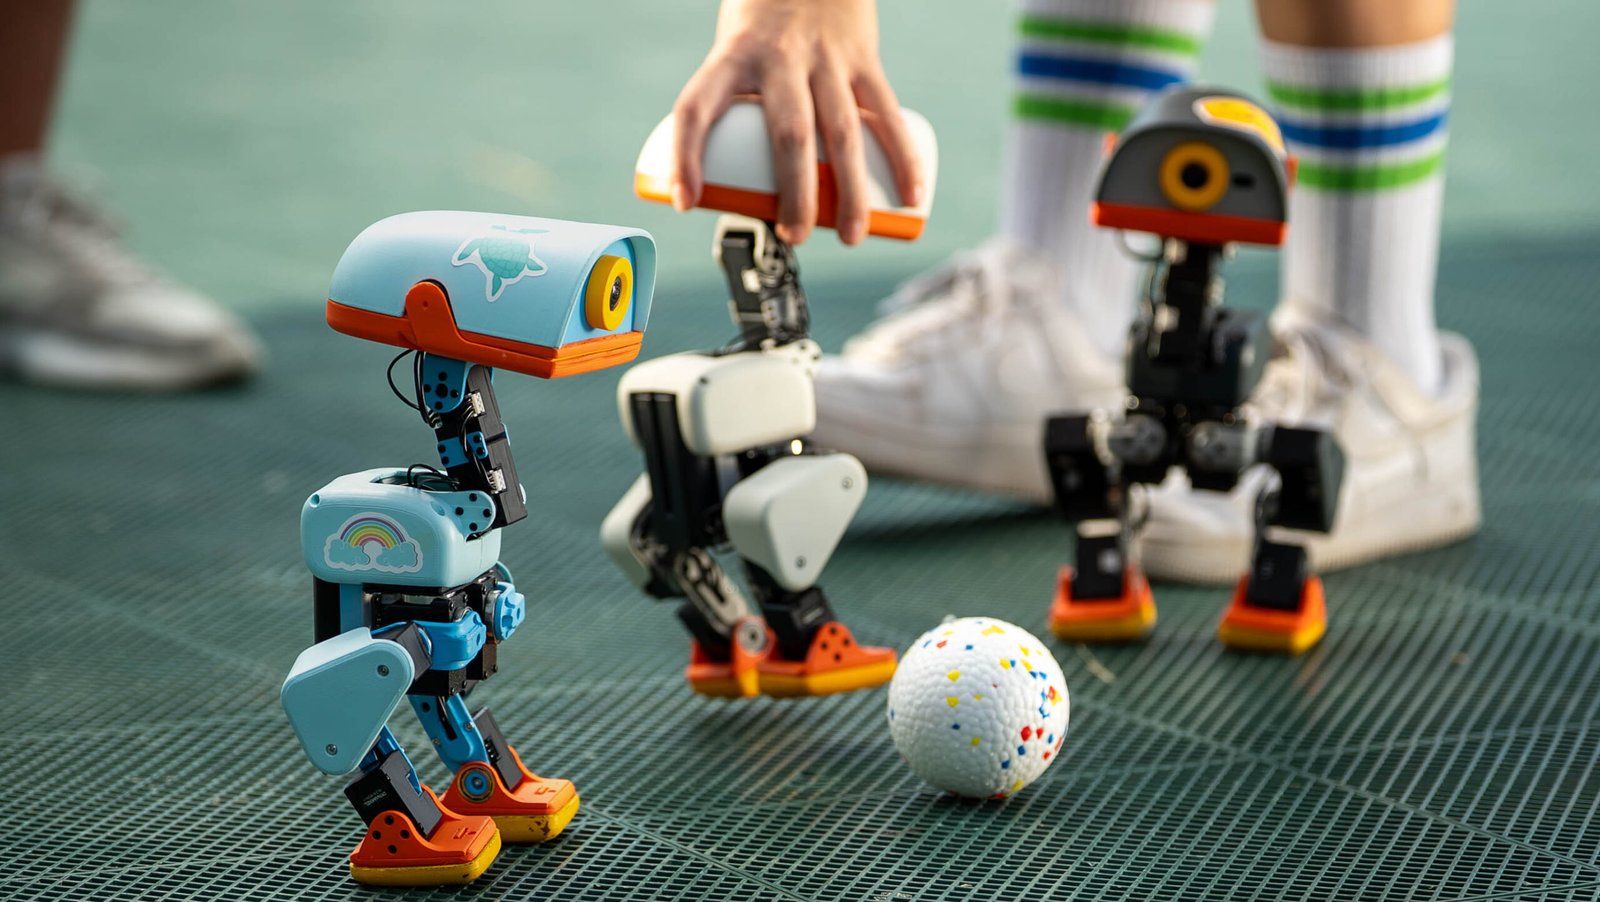
Lead photograph: Microduck, official Pollen Robotics press material. Illustrates one atlas segment; not a factory photograph or evidence of completed deliveries. Photo source.
ROBOMORROW INTELLIGENCE / 02 · 12 NOV 2026
Redakcja RoboMorrow · Public-source analysis · Verified through 12 Nov 2026.
The thesis in 30 seconds
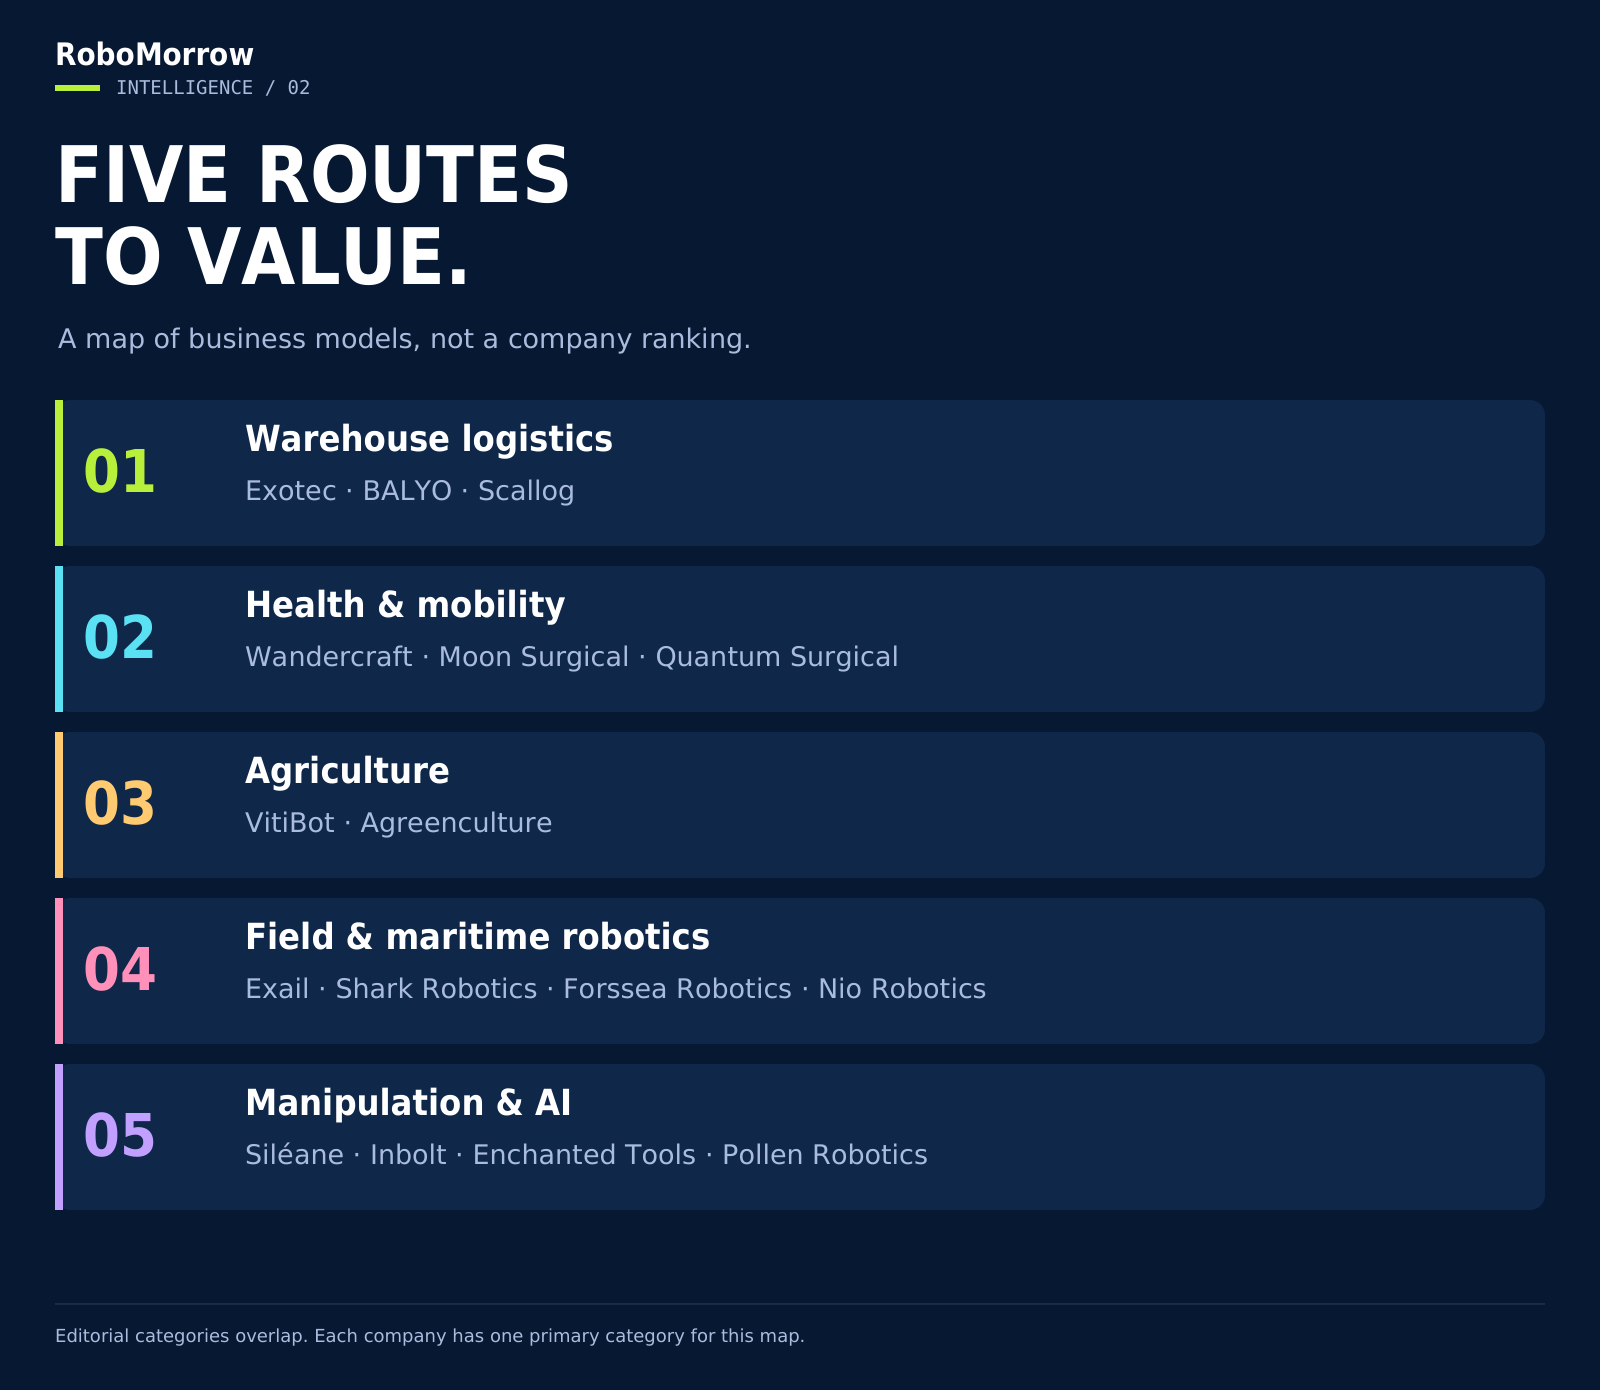
4,500 industrial installations do not describe the whole French robotics economy. Our 16-company map shows five routes to value: warehouses, health, agriculture, field and maritime work, and AI-enabled manipulation. We compare tasks, metrics and evidence without inventing a size ranking.
Inside this analysis
- France does not fit on one chart
- 4,500 installations: an important number with a narrow scope
- Angle 1: a warehouse buys flow, not a robot demonstration
- Angle 2: healthcare has a different route to scale
- Angle 3: from exoskeleton to factory — what actually transfers?
- Angle 4: robotics value also exists outside the factory
- Angle 5: who captures the value of the AI layer?
- France and Germany: compare the same unit
- What to check before the next deployment
France does not fit on one chart
French robotics looks different depending on what you measure. New industrial robot installations describe factory investment. A supplier map identifies capabilities that may be sold worldwide. A humanoid video shows a particular demonstration. None of these replaces the others.
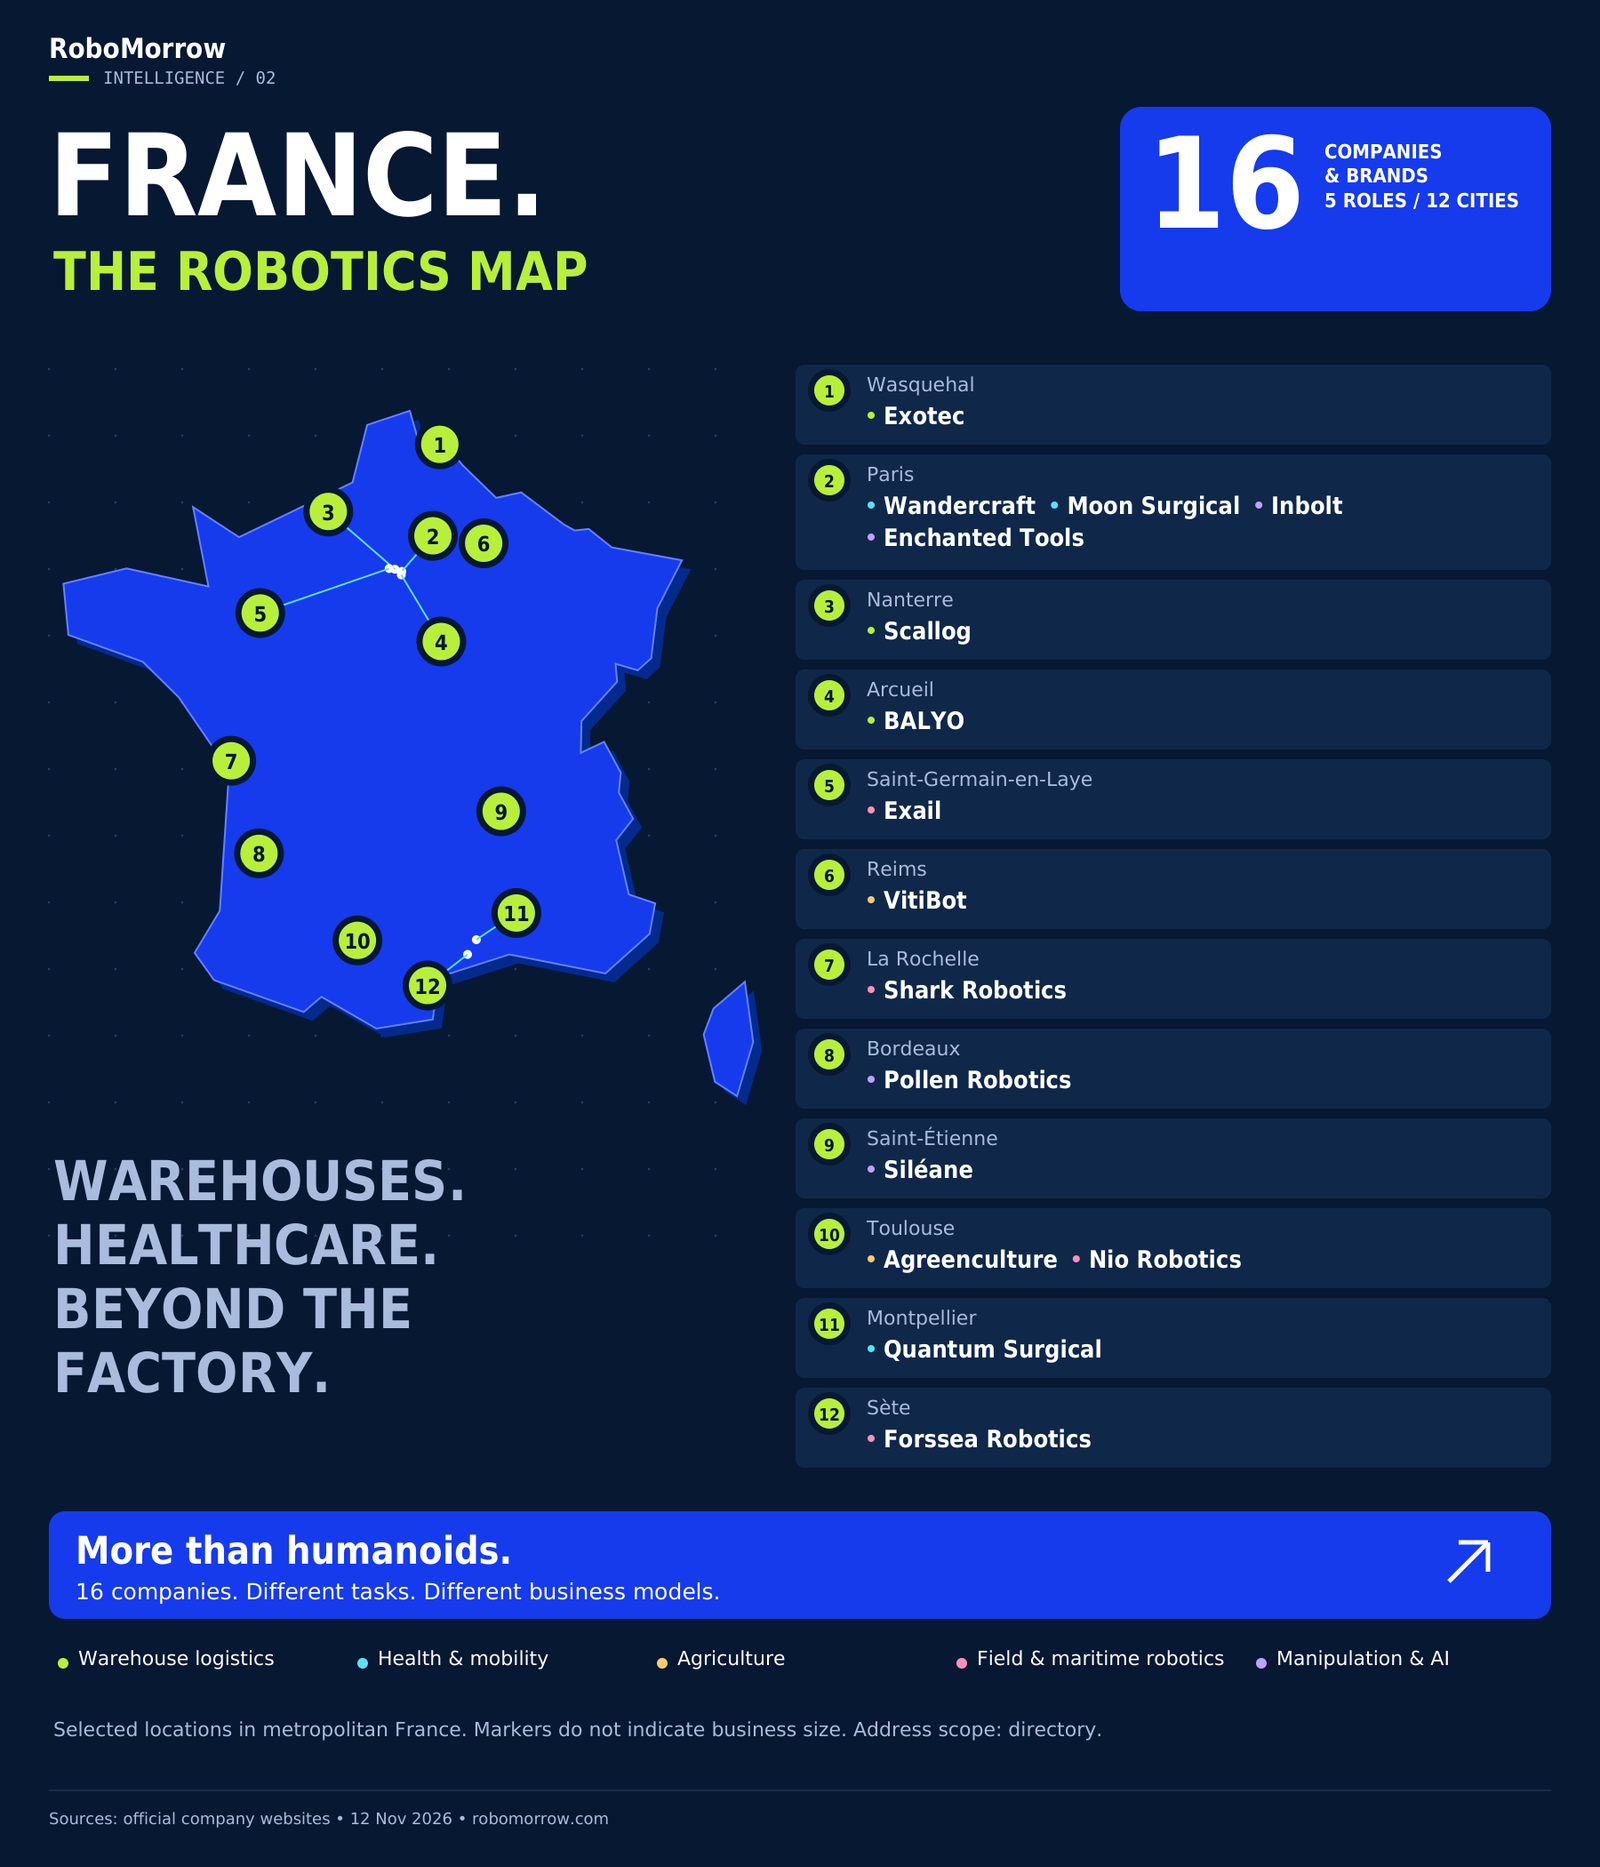
Our thesis: analyze the French ecosystem through tasks and routes to market. Exotec competes for warehouse flow; Moon Surgical for a place in the surgical workflow; VitiBot for vineyard work; Forssea for access to subsea infrastructure. The common denominator is not the robot’s shape. It is the ability to perform useful work under defined conditions.
This atlas covers 16 selected companies and brands across 12 locations. It is not an exhaustive census, a revenue ranking or a list of independent corporate groups. Categories are editorial tools. We do not invent undisclosed revenue, robot populations or market shares.
4,500 installations: an important number with a narrow scope
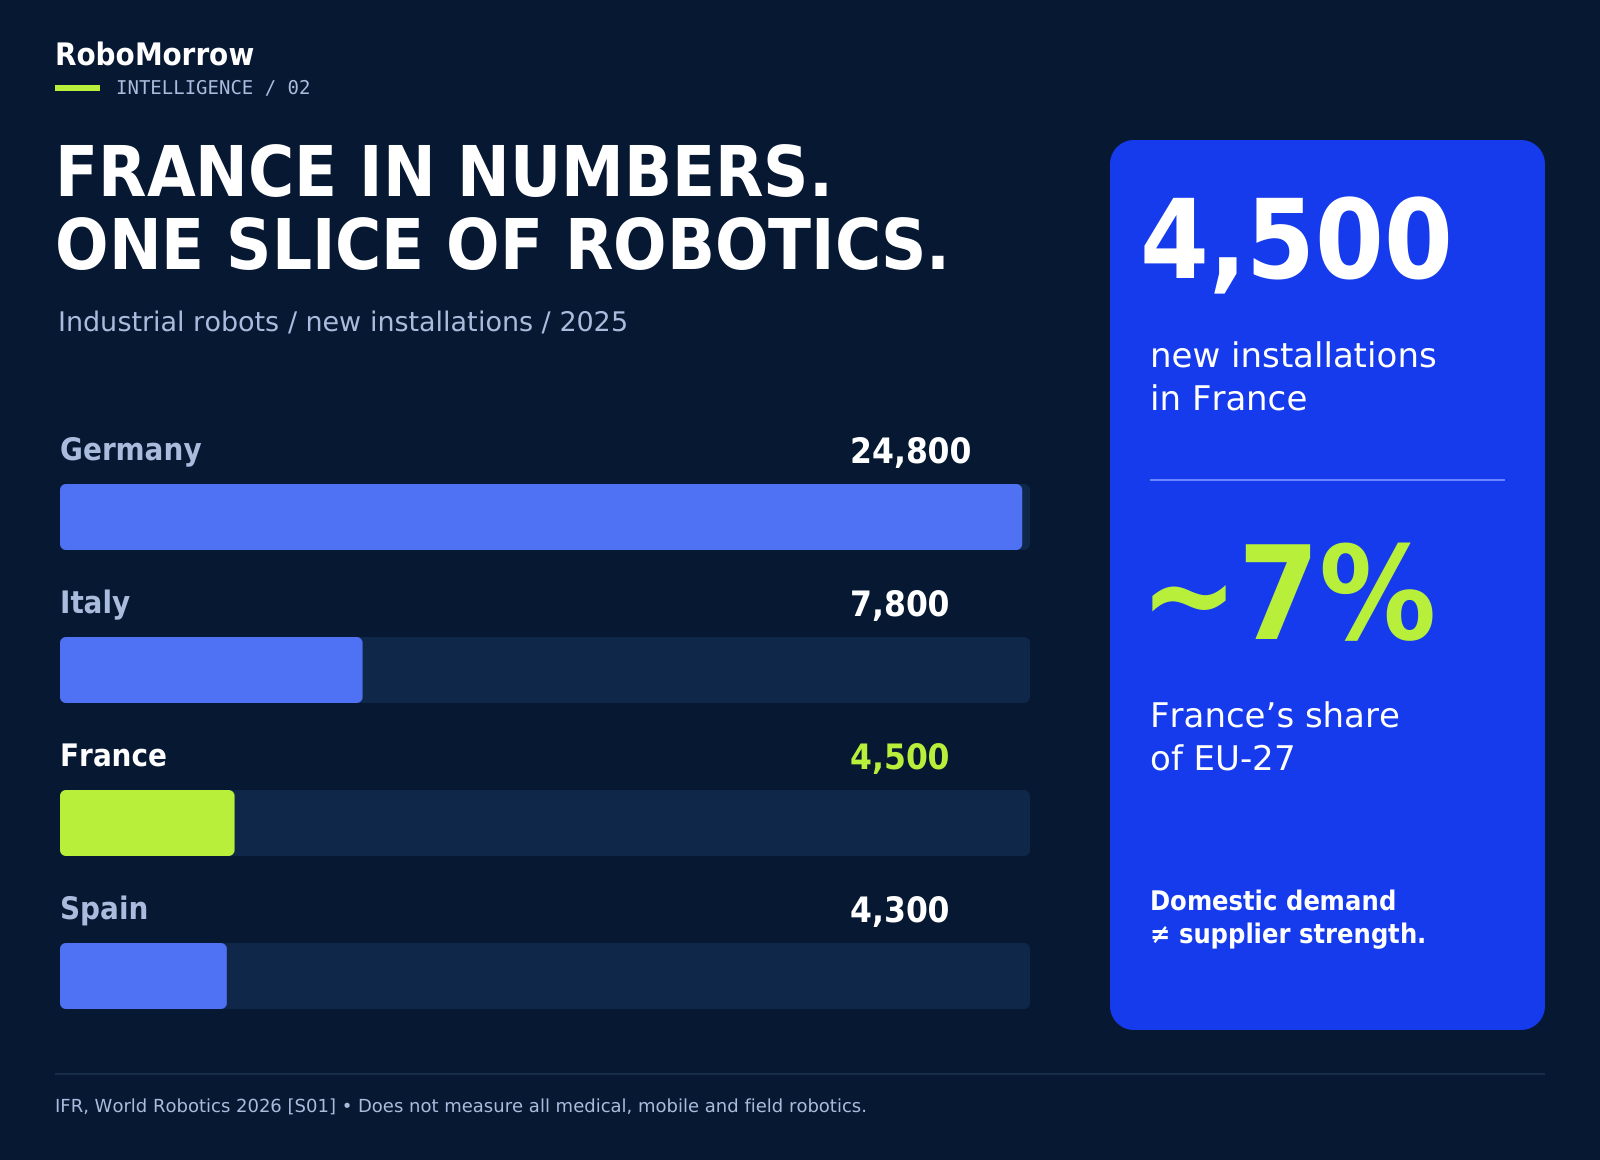
IFR reports 4,500 industrial robot installations in France in 2025. Germany recorded 24,800; Italy 7,800; Spain 4,300. The EU-27 total was 60,500. IFR rounds France’s share to 7%; the Germany-to-France ratio is approximately 5.5. This compares new installations in the same year, not the value of French and German suppliers. [S01]
Automotive accounted for 21% of French demand and metals for 18%. Even within this narrow industrial category, more than half of installations therefore came from other industries. We do not turn those rounded shares into falsely precise robot counts. [S01]
The crucial boundary: this series does not measure the entire medical, warehouse, agricultural and subsea robotics economy. It cannot support the claim that France’s whole robotics business is 5.5 times smaller than Germany’s. It supports a narrower statement: French factories installed substantially fewer robots in the category measured by IFR.
Angle 1: a warehouse buys flow, not a robot demonstration
Exotec, BALYO and Scallog belong on the same map, but they do not offer interchangeable products. Skypod combines robots with storage and picking. BALYO automates pallet movement and storage. Scallog brings shelving to workstations. The relevant competitor depends on the workflow, load dimensions and tasks that remain with people.
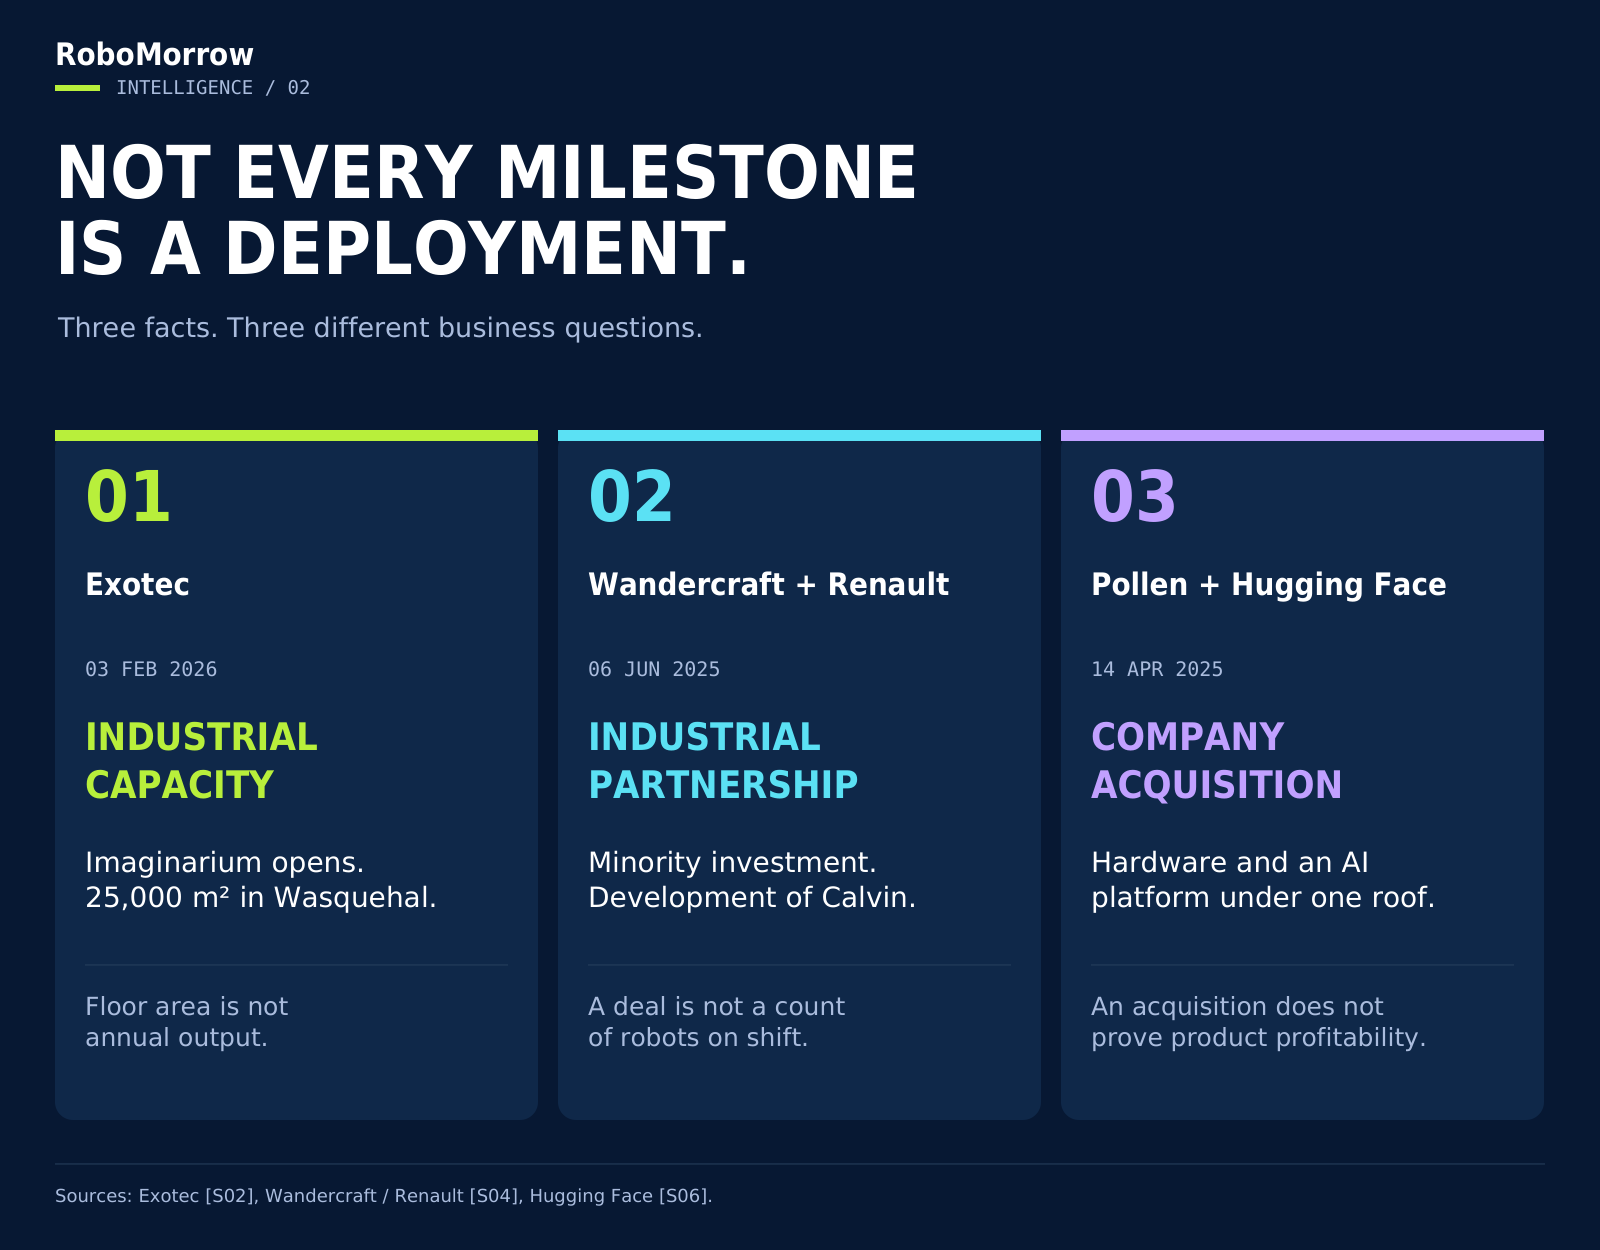
On 3 February 2026, Exotec opened Imaginarium in Wasquehal: 25,000 m² bringing together more than 700 employees. That is evidence of investment in development and industrial capacity. The building’s area does not establish annual robot output or project margins. [S02]
For the buyer, the questions concern a changing order mix, component failure and seasonal peaks. Business analysis should separate hardware, integration, software and ongoing service. A compelling demonstration of retrieving one tote does not establish whole-warehouse performance.
“Imaginarium reflects our commitment to build in Europe and our decision to invest for the long term.”
Renaud Heitz, CTO and co-founder, Exotec · 2026-02-03. Excerpt from a published statement. [S02]
Angle 2: healthcare has a different route to scale
Wandercraft, Moon Surgical and Quantum Surgical address different tasks: mobility assistance, laparoscopic assistance and support for minimally invasive cancer treatment. Axis count, arm speed and resemblance to a person are poor common denominators. The relevant unit is a specific workflow, clinical user and authorized application. [S10] [S11]
On 1 October 2026, Wandercraft announced the completed acquisition of Ekso Bionics. Its statement describes more than 700 rehabilitation centers worldwide served collectively by Atalante X and EksoNR. This is the combined reach of two platforms: not 700 robots sold that year, not 700 French hospitals and not a Calvin-40 installation count. [S05]
Our business interpretation: an acquisition can provide teams, clinical relationships and service channels. It does not itself establish profitability or clinical superiority. Buyers and investors need application-specific information on utilization, training, support, financing and outcomes. This analysis is not an assessment of treatment effectiveness.
Angle 3: from exoskeleton to factory — what actually transfers?
Renault Group and Wandercraft announced their partnership on 6 June 2025. It combines a minority investment with development of the Calvin robot family, initially for Renault’s industrial applications. The announcement also describes plans to use the carmaker’s industrialization and cost-reduction expertise. This establishes the agreement’s scope, not mass deployment. [S04]
The interesting angle is therefore more specific than “France has a humanoid.” Can balance and motion expertise developed for medicine be combined with a major customer’s production discipline? Boundaries matter as much as synergies: loads, duty cycles, accountability, acceptance procedures and the cost of failure change across environments.
A competitive advantage needs task-level evidence: availability across a shift, human intervention frequency, execution quality and the time required to transfer the system to another line. Neither the historical partnership announcement nor a video supplies the complete answer.
“Renault Group’s investment marks a defining moment for Wandercraft.”
Matthieu Masselin, CEO and co-founder, Wandercraft · 2025-06-06. Excerpt from a published statement. [S04]
Angle 4: robotics value also exists outside the factory
Agriculture and infrastructure change the return-on-investment calculation. VitiBot supplies Bakus for vineyards; Agreenculture provides autonomy technology to machinery manufacturers. One model can be examined through the work of a specific machine; the other also through technology distributed inside partners’ products. Both require attention to seasonality, terrain, implements and support.
Shark Robotics, Forssea, Exail and Nio Robotics illustrate the value of access to demanding environments. Not every mission needs full autonomy. Remote operation can be useful when a person no longer needs to enter a hazardous zone. Nio’s current Aru page distinguishes capabilities labeled live from welding still in development. We preserve that distinction. [S09]
Exail Technologies reported €478.545 million in group revenue for 2025 and €844 million in order intake that year. These are different measures. The group includes maritime robotics, navigation and other technologies; its entire revenue must not be presented as the value of the “French robot market.” [S03]
In these sectors, examine the cost of a completed mission, crew mobilization and infrastructure downtime. A robot’s purchase price can omit the largest part of the economic case.
Angle 5: who captures the value of the AI layer?
Inbolt develops vision and AI guidance for robots; Siléane combines such capabilities in machines performing manipulation. Enchanted Tools develops Mirokaï for human environments, while Pollen Robotics connects hardware platforms with a developer ecosystem. These are different ways to commercialize intelligence, not one comparable product.
On 14 April 2025, Hugging Face announced its acquisition of Pollen Robotics. This suggests an interesting analytical lens: hardware can become an entry point for developers, data and tools. It does not mean every open project automatically has a cost advantage or a proven revenue model. [S06]
The lead photograph shows real Microduck robots from Pollen’s official press material. As of 12 November 2026, the press kit describes pre-orders opened on 27 August and first deliveries targeted before Christmas. That is a delivery target, not evidence of a delivered fleet. The manufacturer also specifies that the open-source claim covers software, not mechanical or electronic design files. [S07]
The business question is whether the customer pays for a platform, a completed task, integration or maintenance. That determines who bears adaptation costs and who captures value from the next deployment.
“We believe robotics could be the next frontier unlocked by AI — and it should be open, affordable, and private.”
Thomas Wolf, Co-founder and chief scientist, Hugging Face · 2025-04-14. Excerpt from a published statement. [S06]
France and Germany: compare the same unit
France has a substantially smaller domestic flow of new industrial robot installations. That fact does not rank every supplier, the quality of technology or future winners. Our French selection includes many applications outside conventional factory automation, but selecting 16 companies is not statistical proof of a national specialization.
Business nationality also needs care. Team location, customer country and capital ownership can differ. Pollen belongs to Hugging Face, VitiBot to SDF, and Moon Surgical operates across the Atlantic. Attaching a flag does not establish where revenue originates or which group consolidates it. [S06] [S08] [S10]
We therefore do not add valuations, orders, revenue and funding together. For most selected companies, we lack a uniform, comparable financial dataset for the same year and business perimeter. An absent number means missing comparable information, not zero.
| Metric | Value | Scope and limitation |
|---|---|---|
| France | 4,500 | New industrial robots, 2025; not company sales. [S01] |
| Exail Technologies | €478.545m | Global group revenue, 2025; includes navigation and other technologies. [S03] |
| BALYO | €31.4m | Company revenue, 2025; pallet-handling automation. A different scope from Exail. [S12] |
| Exail Technologies | €844m | Order intake, 2025; not revenue recognized that year. [S03] |
| Wandercraft + Ekso | 700+ | Rehabilitation centers worldwide, October 2026; not a robot count. [S05] |
This is a comparison of definitions, not a ranking. Even same-year revenue requires checking consolidation scope and the robotics share of each business.
What to check before the next deployment
The most useful commercial conversation starts with one task and its acceptance conditions. Define the correct result, error tolerance, duty cycle, interfaces and integration responsibilities. Ask for evidence from a comparable process, not the company’s aggregate customer count.
For a warehouse, the relevant measure may be cost per correctly completed order at peak load. For infrastructure, cost per safely completed mission. For a hospital, system utilization and the requirements of its specific workflow. These are suggested analytical questions, not performance claims about the suppliers listed here.
The second site is especially informative. It reveals how much integration must be repeated, how service works and whether lessons from the first deployment reduce the cost of the next. French robotics offers many interesting entry points. The strongest business is identified through repeatable value, not the most dramatic frame.
Directory: 16 companies and brands
16 / 16 companies and brands
Exotec
WasquehalSkypod robots, storage and order-picking systems. The Imaginarium headquarters opened in February 2026; the business is warehouse flow, not a standalone robot.
Selected company / brand; this is not a size ranking.
BALYO
ArcueilAutonomous forklifts for pallet transport and storage. The load geometry and workflow differ from Exotec tote systems or Scallog mobile shelving.
Part of SoftBank’s ecosystem; majority control described in the March 2026 results release.
Scallog
NanterreMobile robots bring shelving to picking stations. Meaningful comparisons require the SKU mix and peak workload, not just a robot count.
Selected company / brand; this is not a size ranking.
Wandercraft
ParisMedical exoskeletons and the industrial Calvin-40. The Renault partnership connects motion expertise with industrialization; the agreement alone does not prove deployment scale.
Ekso Bionics acquisition announced and closed on 1 Oct 2026. Ekso is not counted separately.
Moon Surgical
ParisRobotic assistance for laparoscopic surgery. Maestro supports the operating-room team; it should not be described as an autonomous surgeon.
Franco-American organization; the marker locates Paris.
Quantum Surgical
MontpellierRobotic assistance for minimally invasive cancer treatment. Commercial qualification must consider the specific indication and authorization in each market.
Selected company / brand; this is not a size ranking.
VitiBot
ReimsBakus electric vineyard robot. Row geometry, terrain and implements define the application; seasonality shapes operating economics.
An SDF Group company.
Agreenculture
ToulouseAutonomy systems for machinery and tractor manufacturers. This includes supplying technology for another OEM’s machine, rather than only selling a proprietary robot.
Selected company / brand; this is not a size ranking.
Exail
Saint-Germain-en-LayeMaritime robotics, navigation and broader technologies. The marker uses Exail Holding’s address; the group has multiple sites and its revenue is not pure robotics revenue.
Selected company / brand; this is not a size ranking.
Shark Robotics
La RochelleRobots for firefighting, security and hazardous missions. Remote operation can be the appropriate operating mode; it should not be equated with full autonomy.
Selected company / brand; this is not a size ranking.
Forssea Robotics
SèteSubsea robotics and vision systems. The official website lists headquarters in Sète and an office in Versailles; the map uses the headquarters.
Selected company / brand; this is not a size ranking.
Nio Robotics
ToulouseAru platform for work in confined infrastructure. The manufacturer distinguishes live capabilities from welding, which remains in development.
Current manufacturer name; formerly Nimble One.
Siléane
Saint-ÉtienneMachines combining robotics, vision and AI for manipulation in variable conditions. The purchase is process execution, not an AI model alone.
Selected company / brand; this is not a size ranking.
Inbolt
Paris3D vision and AI for industrial robot guidance. Value can come from improving the flexibility of an existing robot arm.
Selected company / brand; this is not a size ranking.
Enchanted Tools
ParisMirokaï robots for manipulation in human environments. Partnerships and demonstrations are not a standardized measure of paid installations.
Selected company / brand; this is not a size ranking.
Pollen Robotics
BordeauxRobot platforms and a developer ecosystem. Microduck: pre-orders from August 2026, first deliveries targeted before Christmas; its open-source claim covers software.
Part of Hugging Face since April 2025.
How to read this map
Purposive selection: an active robotics offering or program, identifiable operations in France and public sources. One primary category per company; applications may overlap. Points mark approximate city centers, not exact factory coordinates. Exail uses its holding address; Moon Surgical uses the French location of a transatlantic organization. The map covers metropolitan France. Marker size encodes neither revenue nor headcount. We did not conduct hands-on product tests.
Categories, procurement questions and comparative conclusions are editorial analysis. Figures and events are attributed to sources. Quotes reproduce excerpts of published statements; dates are given alongside them. We do not turn unavailable private data into estimates presented as measurements.
Continue reading on RoboMorrow
Sources and dates
- IFR — EU industrial robot installations, World Robotics 2026 — 2026-09-24.
- Exotec — Imaginarium headquarters opens in Wasquehal — 2026-02-03.
- Exail Technologies — FY2025 annual results — 2026-03-18.
- Wandercraft / Renault Group — Introducing Calvin-40 — 2025-06-06.
- Wandercraft — acquisition of Ekso Bionics — 2026-10-01.
- Hugging Face — Pollen Robotics acquisition — 2025-04-14.
- Pollen Robotics — Microduck press kit — accessed 2026-11-12.
- VitiBot — subsidiary of SDF Group — accessed 2026-11-12.
- Nio Robotics — Aru and application maturity — accessed 2026-11-12.
- Moon Surgical — Maestro and company news — accessed 2026-11-12.
- Quantum Surgical — Epione — accessed 2026-11-12.
- BALYO — FY2025 results — 2026-03-16.
Company addresses and offerings: sources in the directory cards. Maps and infographics: Redakcja RoboMorrow. Simplified boundary: world.geo.json (Johan Sundström), https://github.com/johan/world.geo.json.
Explore the whole Robotics Nations series
Three complementary perspectives on robotics companies and business models. Each map covers a selected group of 16 companies or brands, not a complete national market.
- Germany — company map
Industry, components and the route from pilot to deployment. Published 12.11.2026; research cut-off 11.11.2026. - France — company map
Warehouses, healthcare, agriculture and software. Published 13.11.2026; research cut-off 12.11.2026. - USA — company map
Humanoids, logistics, healthcare and AI models. Published 14.11.2026; research cut-off 14.11.2026.
Robotics Nations — all maps and earlier analyses →
Get future robotics market analyses in the RoboMorrow newsletter →